A Housing Market of Contradictions
The late summer housing market is defined by a key contradiction: mortgage rates have fallen to their lowest point since April, boosting buyer affordability, but this relief is a direct result of a stalling national labor market. July’s jobs report showed negligible growth after massive downward revisions for May and June, cooling the economy and pushing down borrowing costs. This dynamic creates a “stuck” market where improved affordability is met with economic uncertainty, eroding consumer confidence. As a result, forward-looking indicators like pending home sales show persistent declines, suggesting the market has yet to find momentum. In this August 2025 housing market update, we break down the latest mortgage rate shifts, buyer behavior, and forward-looking economic trends.
The Economic Backdrop: Cooling Inflation and a Stalling Jobs Engine
The economy is sending conflicting signals that are shaping the housing market. A significant slowdown in the labor market is pushing mortgage rates down, while stubborn inflation creates uncertainty about the Federal Reserve’s future policy.
The Labor Market’s Warning Shot
The July jobs report revealed a significant economic slowdown. While the unemployment rate held at 4.2%, payrolls grew by a mere 73,000. More importantly, massive downward revisions for May and June erased a combined 258,000 previously reported jobs, showing the economy was stagnant through the spring. This lack of job creation, a key driver of housing demand, is amplified by a rise in long-term unemployment and a declining labor force participation rate. This weakness erodes consumer confidence, likely offsetting some of the benefits of lower mortgage rates.
Inflation’s Stubborn Plateau
Despite the cooling labor market, inflation remains stubbornly above the Federal Reserve’s 2% target. The Producer Price Index showed that both headline and core inflation rose by 0.3%, which was much hotter than the 0.2% expected. It does appear that the tariffs are finally showing up in the data…but taking yesterday’s CPI and PPI reports together, we can derive that a lot of the cost is currently being absorbed along the supply chain. This puts the Fed in a difficult position: the weak job market calls for rate cuts, but high inflation calls for holding steady. This conflict creates uncertainty and suggests the current low-rate environment may be a temporary window for buyers.
The Rate Retreat: A Quantifiable Boost to Affordability
Mortgage rates have fallen significantly, providing a tangible boost to affordability. The average 30-year fixed rate dropped to 6.63% in early August, its lowest level since April. This retreat from May’s peak has a quantifiable impact: a buyer with a $3,000 monthly budget can now afford a home worth about $20,000 more. The market has responded immediately, with mortgage applications rising 2% week-over-week and up 18% from last year, demonstrating that pent-up demand is highly sensitive to rate changes.
August 2025 Housing Market Update: Rebalancing Across Regions
The national housing market is clearly cooling and rebalancing, though the process is uneven across the country. It is critical to look at forward-looking data to understand the current trajectory.
Sales and Pricing: A Tale of Two Timelines
Recent housing data can be misleading. While June’s median sale price hit a record $435,300, this is a lagging indicator reflecting contracts signed in the spring. More current, forward-looking data shows a cooling market. The Pending Home Sales Index fell in June, signaling weaker sales ahead. Furthermore, median asking prices in early August saw one of their smallest year-over-year gains in two years, and list prices are already declining in the South and West, indicating that seller leverage is fading.
Inventory and Time on Market: More Choice, Less Urgency
Buyers now have more choices, as the inventory of homes for sale rose 24.8% year-over-year in July. However, this is a “passive” increase driven by cooling demand, not a flood of new sellers; new listings remain flat. Homes are simply sitting on the market longer—a median of 58 days in July, a full week longer than last year. This has allowed supply to accumulate to 3.9 months, moving closer to a balanced market. The market is characterized by stagnation, not a supply glut, making the rebalancing fragile.
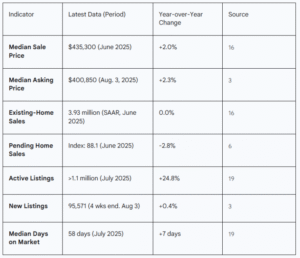
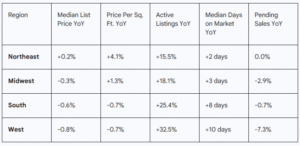
August 2025 Housing Market Update Chart Sources Above: Realtor.com (July 2025) for Price, Listings, and Days on Market; NAR (June 2025) for Pending Sales
Key Market Indicators
| Indicator | Value | Change |
| 30-Year Fixed Mortgage Rate | 6.63% | Lowest since April |
| Median Sale Price (June) | $435,300 | Record high |
| Inventory (July) | — | +24.8% YoY |
| Days on Market (July) | 58 days | +7 days YoY |
| Months of Inventory | 3.9 months | Approaching balance |
| Pending Home Sales (June) | — | Declining |
The Human Element: Decoding Buyer and Seller Behavior
Underlying the market statistics are powerful demographic trends that explain the market’s resilience and its contradictions. A generational wealth transfer and a rebound in foreign investment are creating a strong price floor.
The Great Wealth Transfer: Boomers Take the Lead
A major generational shift is reshaping the market. Baby Boomers (ages 60-78) are now the largest group of homebuyers at 42%, overtaking Millennials. Leveraging decades of home equity, nearly half of Boomer buyers pay in all-cash, putting a floor under prices. This has made it difficult for younger, financing-dependent buyers, whose share of the market has fallen to a historic low of 24%. This dynamic explains the paradox of high prices coexisting with a severe affordability crisis.
The Return of the International Buyer
Adding to demand, foreign investment in U.S. homes surged 33% to $56 billion. Buyers from China, Canada, and Mexico lead the trend, concentrating their purchases in states like Florida, California, and Texas. Like Boomers, nearly half of these buyers pay in cash and purchase more expensive properties, providing another layer of price support in key markets.
Buyer & Seller Demographics
| Category | Statistic |
| Dominant Buyer Group | Baby Boomers: 42% (Millennials: 29%) |
| Cash Buyers (Boomers) | Nearly 50% all-cash purchases |
| First-Time Buyers | Historic low: 24% |
| International Buyers | $56B in U.S. real estate (33% surge) |
| Foreign Cash Buyers | Nearly 50% all-cash purchases |
Policy Watch: Washington’s Bipartisan Push on Housing Supply
In a significant policy shift, Washington is showing rare bipartisan consensus to tackle the housing crisis by focusing on supply, not just demand. Two key bills lead this effort.
The One Big Beautiful Bill Act boosts affordable housing construction by expanding tax credits and easing financing for developers. More comprehensively, the Renewing Opportunity in the American Dream (ROAD) to Housing Act of 2025 passed unanimously out of its Senate committee and aims to break down local barriers to construction by incentivizing zoning reform, streamlining permitting, and reducing regulatory burdens. This long-term strategy to build more homes could eventually ease the inventory shortage and create new opportunities across the housing industry.
Concluding Analysis & Forward Outlook
The housing market will remain “stuck” for the rest of 2025, caught between the opposing forces of lower rates and a weaker economy. While a major price crash is unlikely due to a price floor set by cash-heavy Boomer and international buyers, the market is clearly rebalancing. Transaction volume will stay low, and national home prices are forecast to remain flat or decline slightly.
For Homebuyers: Cautious Opportunity
Lower rates, more inventory, and greater negotiating power create the best buying conditions in over a year. However, economic uncertainty demands financial prudence.
For Home Sellers: Strategic Realism
The peak of seller power has passed. Price your home for today’s market, not last spring’s. Be prepared for longer days on market and negotiations.
Sources
- Mortgage Rates Continue to Decrease – GlobeNewswire, accessed August 12, 2025
- U.S. Mortgage Rates Dip to Four Month Low in Early August – The World Property Journal
- Buyers, Take Note: Mortgage Rates Are Falling, Home-Price Growth – Redfin
- Employment Situation Summary – 2025 M07 Results – BLS
- Pending Home Sales Drop in June as Buyers Struggle With Affordability – Realtor.com
- NAR Pending Home Sales Report Shows 0.8% Decrease in June – GlobeNewswire
- July 2025 Housing Market Trends Report – Realtor.com Research
- Four Takeaways from NAR’s New Generational Trends Report
- 2025 International Buyers in U.S. Real Estate – NAR Report
- Federal Housing Policy Update – California Council
- Banking Committee Passes Bipartisan ROAD to Housing Act – NLIHC
- United States Housing Market & Prices – Redfin